The Snowball Analytics
Retirement Calculator
Model your accumulation phase, calculate your required nest egg, compare capital drawdown vs living on dividends, and simulate inflation-adjusted purchasing power.
The retirement calculator helps you work out:
Required Nest Egg Size
How much capital you need to accumulate before leaving the workforce.
Drawdown vs. Dividends
The difference between selling assets (4% SWR) vs living strictly on dividend income.
Inflation-Adjusted Income
How purchasing power erosion affects your future living expenses over 20–30 years.
Portfolio Longevity
Whether your savings will last through age 90+ and when your growth exceeds contributions.
$0
Nest Egg at Retirement
$0
Target Needed
$0
Monthly Income at Retirement
$0
Real Value (Today's $)
Year-by-Year Projection
Pro-Tips for Long-Term Investors
Actionable compounding strategies to maximize portfolio efficiency and build a durable retirement nest egg.
Tax-Advantaged Accounts
Eliminate annual tax drag by holding yield assets in tax-sheltered accounts: Roth IRA & 401(k) (US), ISA & SIPP (UK), TFSA & RRSP (Canada), or Superannuation (Australia). Reinvest gross payouts without tax friction.
Living on Dividends Strategy
Mitigate market downturn risk early in retirement by relying on cash dividend yields rather than liquidating stocks during market drawdowns. Preserving your principal ensures your portfolio outlasts your retirement horizon.
Annual Contribution Step-Up
Increase your periodic savings additions by 3%–5% each year in step with salary growth. Flat contribution amounts lose real purchasing power over 20+ years, while step-up indexation keeps compounding far ahead of inflation.
Explore Top Investing Concepts for Retirement
Understand how long-term wealth accumulators leverage compounding structures
More Financial Tools & Calculators
Optimize your portfolio further with our specialized long-term planning tools.
Dividend Calculator
Project future dividend payouts, simulate DRIP plans, and calculate your Yield on Cost.
S&P 500 Calculator
Model historical index returns, reinvest dividends, and run simulations for SPY/VOO.
Compound Interest
Calculate compound interest with daily ledger precision, tax drag, and inflation.
FIRE Calculator
Calculate your Financial Independence number and predict when you can retire early.
Explore the Snowball Analytics ecosystem
Dive deeper into the tools behind the tracker — from stock analysis to dividend planning
Dividend tracker
Automatically track payouts, calculate Yield on Cost, and project future passive income.
Explore dividend tracker →Dividend rating
Avoid yield traps. Analyze financial health,payout ratio and sustainability.
Check dividend ratings →Stock tracker
Monitor individual equities, price movements and 10-year company fundamentals.
Explore stock tracker →Dividend calendar
See exactly when payouts hit your account across all global holdings.
View dividend calendar →Dividend calculator
Project future passive income, simulate DRIP scenarios and visualize compounding.
Try dividend calculator →Ex-dividend calendar
Plan trades around upcoming ex-dividend dates to capture the next payout.
View ex-dividend dates →Professional Retirement Engine
Typical calculators only model accumulation. The Snowball Analytics Retirement Calculator features a dual-phase engine modeling accumulation, decumulation, inflation discount, tax drag, and dividend preservation.
Snowball Analytics vs. Basic Online Retirement Calculators
Long-term retirement planning requires modeling real-world financial friction. Here is how our dual-phase engine compares to simple tools.
| Feature / Capability | Snowball Analytics | Basic Online Calculators |
|---|---|---|
| Dual-Phase Modeling (Accumulation + Decumulation / Drawdown) | Yes | ✕ |
| Living on Dividends Strategy (Principal Preserved) | Yes | ✕ |
| Portfolio Longevity & Nest Egg Depletion Age Calculation | Yes | ✕ |
| Inflation Purchasing Power Discounting (Real Dollars) | Yes | ✕ |
| Annual Contribution Step-Up / Salary Growth Indexation | Yes | ✕ |
| Income Tax Drag Modeling during Accumulation Years | Yes | ✕ |
| Milestones, Tipping Points & Depletion Age Calculation | Yes | ✕ |
Frequently Asked Questions
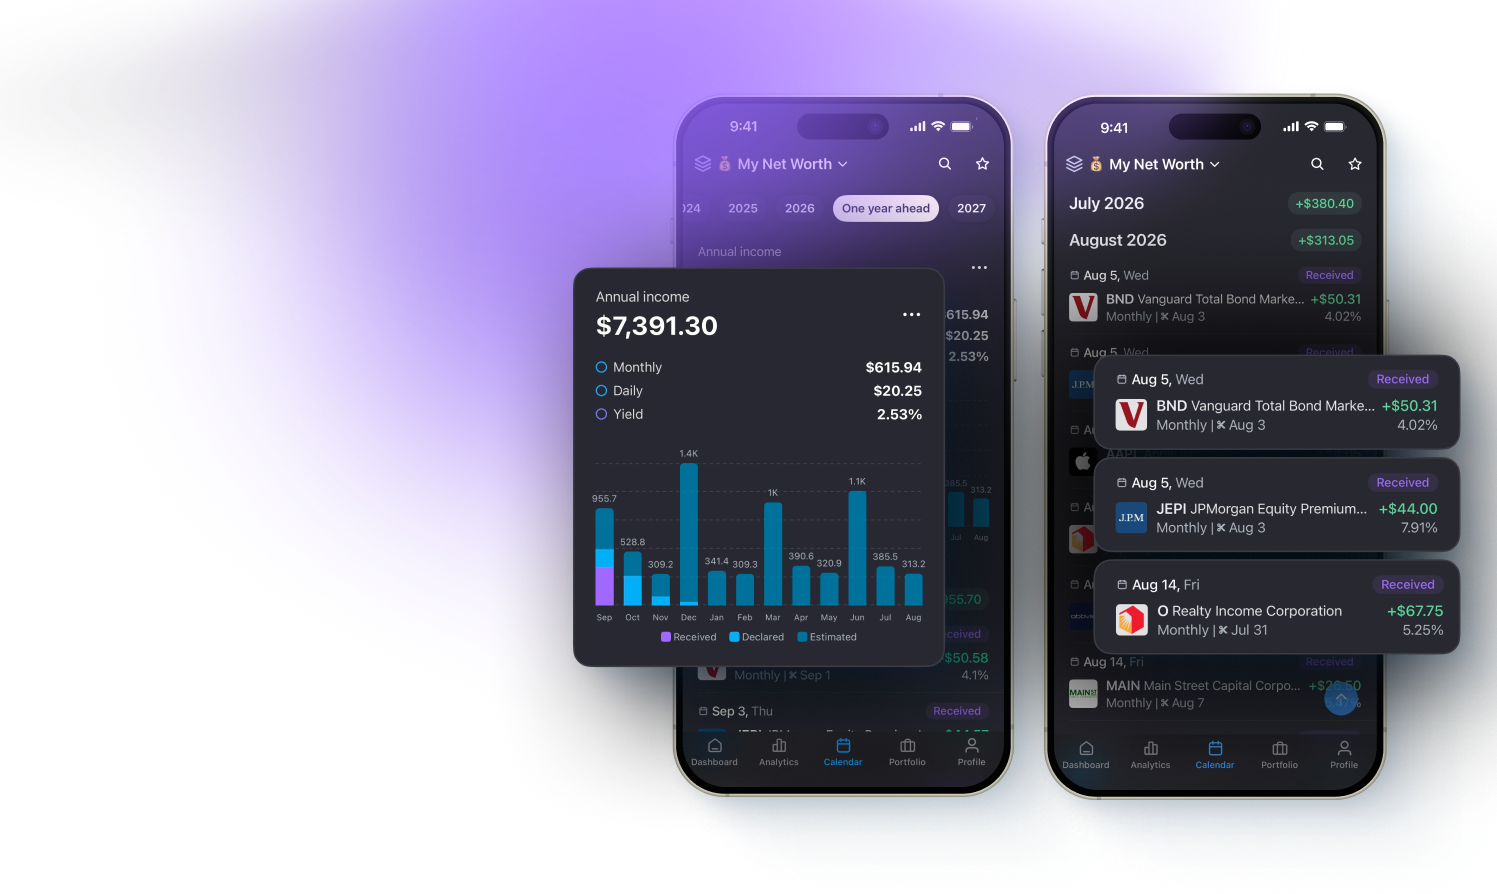
Your portfolio dashboard, anywhere
Take control of your investments with the Snowball Analytics mobile app. Everything you love about the web tracker, fully optimized for your smartphone.
Ready to Track Your Investment Snowball?
Use this calculator to plan, and create a free Snowball Analytics account to track your actual portfolio performance.
Start for free — no card required View a live demo portfolioBeyond Accumulation: Two Phases of Retirement Planning
Most online retirement calculators only focus on building wealth up to age 65, ignoring what happens when you actually stop working. A realistic plan must account for both the Accumulation Phase and the Decumulation Phase, factoring in Inflation Erosion, Tax Drag, and Sequence of Returns Risk.
The Hidden Frictions on Retirement Wealth
- Annual Tax Drag: In taxable investment accounts, interest, dividends, and realized gains are taxed annually. A 15% tax drag on investment gains can reduce your accumulated nest egg by 20% to 25% over a 30-year working career.
- Inflation Discounting: A nominal $1,500,000 nest egg in 30 years sounds generous, but at a 3% inflation rate, its actual purchasing power equals $617,000 in today's dollars. Our calculator automatically discounts all future numbers to show real value.
- Sequence of Returns Risk: Experiencing a market crash in the first 3 years of retirement while actively withdrawing 4% per year can permanently destroy a portfolio. Living on dividends mitigates this risk by avoiding liquidating shares at rock-bottom prices.
Capital Drawdown vs. Living on Dividends
Retirees must choose how to extract income from their accumulated wealth:
Two Distinct Withdrawal Philosophies
- Capital Drawdown (The 4% Rule): You systematically sell off stock and bond shares every year to generate living cash. While effective, it relies on market stability and leaves your principal balance declining over time.
- Living on Dividends (Principal Intact): You construct a high-quality dividend growth portfolio (using ETFs like SCHD or dividend aristocrats like KO and JNJ). Your retirement check is funded entirely by cash dividend distributions, leaving your underlying shares untouched.